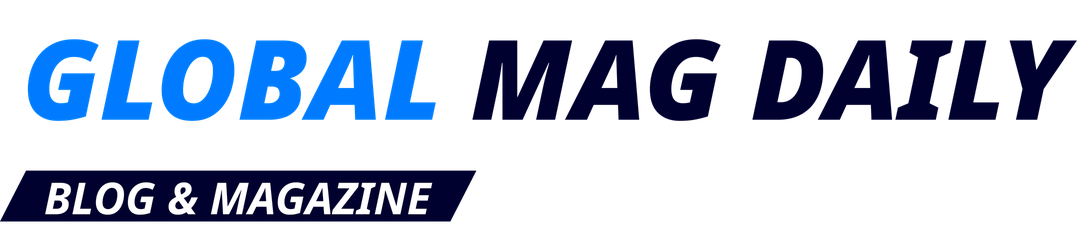

Buying your first house is one of the biggest money decisions you will ever make, and it can feel exciting and scary at the same time. There are new words to learn, big numbers to understand, and many steps between saving your first dollar and getting the keys. This buying a house guide will walk you through the whole journey, from checking your money to closing day, so you can buy with confidence instead of guesswork.
Before we start, remember that every buyer is different. Your budget, your city, and your timing will shape the details. What stays the same is the order of the steps: check your money, save a deposit, get pre-approved, search with a clear list, make a careful offer, and close with help from people you trust.
Is Buying a House Right for You Right Now
The first question is not which house to buy, but whether now is the right time. Buying makes sense when you plan to stay in one place for at least five years, your income is steady, and you have savings beyond the down payment. If you may move soon or your job is uncertain, renting a little longer can be the smarter choice.
It also helps to know the true cost of owning. A mortgage is only part of it. You will also pay for insurance, taxes, repairs, and upkeep. A good rule is to keep your total housing costs below about 30 percent of your take home pay. If the numbers feel tight, give yourself a few more months to save.
Step 1: Check Your Money and Set a Budget
Start by looking honestly at your money. Write down your monthly income after tax, then list your spending on rent, food, transport, bills, and fun. The gap between income and spending is what you can save each month. If you have debts, list those too. Lenders look at your debts when they decide how much to lend you.
Once you know your numbers, set a house budget that fits your life, not just your maximum loan. A good starting point is our guide on how to save money on a low salary, which shows simple ways to find extra money in a tight budget. Small savings add up fast when they happen every month.
Step 2: Build Your Down Payment and Emergency Fund
Most buyers put down between 5 and 20 percent of the house price. A bigger down payment usually means a smaller monthly payment and less interest over time, but a smaller one can still work if it gets you into a home sooner. Aim for at least 10 percent if you can, and keep the money in a savings account you will not dip into for everyday spending.
Just as important is your emergency fund. After you move in, a broken boiler or a leaking roof should not ruin your budget, so keep three to six months of expenses in savings that you do not touch for the house itself. If you need help building that safety net, read our emergency fund guide. The 50/30/20 budget rule is also a simple way to split your income between needs, wants, and savings.
Step 3: Get Pre-Approved for a Mortgage
Before you fall in love with a house, talk to a lender about pre-approval. This is a letter that says how much the bank is likely to lend you, based on your income, debts, and credit history. It shows sellers you are serious and stops you wasting time on houses beyond your reach. Compare at least three lenders, because rates and fees can differ more than you think.
Check your credit report before you apply. You can request a free copy from each major credit bureau, and you should fix any errors you find. Pay your bills on time, keep credit card balances low, and avoid opening new credit in the months before you apply.
Step 4: Start House Hunting With a Clear List
Make two lists before you visit any house: one for must haves and one for nice to haves. Must haves are things you truly need, like three bedrooms, a safe neighborhood, or a short commute. Nice to haves are extras like a big garden or a new kitchen. When you know your must haves, you can say no quickly to houses that do not fit.
Visit each house at least twice, once in daylight and once at another time of day. Check the water pressure, open the windows, look for damp patches, and listen for noise from the street. Ask about heating costs, the age of the roof, and why the owner is selling. Small checks now can save big repair bills later.
Step 5: Make an Offer and Get an Inspection
When you find the right house, your agent will help you make an offer. The price should reflect recent sales of similar houses nearby, not just the asking price. Your offer can include conditions, such as the sale depending on a home inspection or on your mortgage being approved.
Never skip the home inspection. A qualified inspector will check the structure, wiring, plumbing, and roof, and give you a written report. If the report finds problems, you can ask the seller to fix them, lower the price, or walk away. An inspection costs a few hundred dollars but can save you thousands.
Step 6: Closing Day and Moving In
Closing is the day the house legally becomes yours. You will sign the mortgage papers, pay the closing costs, and receive the keys. Closing costs usually add 2 to 5 percent to the price of the house, so keep that money ready. Read every page before you sign, and ask your lawyer or agent to explain anything you do not understand.
Once the keys are in your hand, change the locks on the first day and set up your utilities. Take time to get to know your new home before you buy anything big. A new house does not need to be perfect on day one. Fix the small things first, and enjoy the home you worked so hard to buy.
Common Mistakes First Time Buyers Should Avoid
The most common mistake is spending every dollar you have on the down payment and leaving nothing for moving costs, repairs, or the first months of bills. Another is buying the most expensive house the bank will lend you, which leaves no room for life to happen. Keep a cushion in your budget for surprises.
Other mistakes are easier to avoid: do not skip the inspection, do not change jobs right before closing, and do not open new credit cards or loans while your mortgage is being processed. Any big change to your money can delay or even cancel your approval, so stay steady and let your team guide you.
Frequently Asked Questions
How much money do I need to buy my first house?
Most buyers need a down payment of 5 to 20 percent of the price, plus closing costs of 2 to 5 percent, and an emergency fund of three to six months of expenses. On a 200,000 dollar home, that can mean 20,000 to 40,000 dollars in savings. Start with a budget and save monthly, even small amounts.
How long does it take to buy a house?
From the first saved dollar to the keys, it can take a few months to a few years, depending on your savings and the market. Once you find a house and make an offer, closing usually takes 30 to 60 days. Having your documents ready and a pre-approval in place can keep things moving.
Should I buy a house or keep renting?
Buy when you plan to stay put for at least five years, your income is steady, and you have savings for the down payment and emergencies. Rent when you may move soon, your job is uncertain, or you would rather keep your money flexible. Both can be right, at different times in life.
Conclusion
Buying a house is a big journey, but it is made of small, simple steps. Check your money, save a deposit, get pre-approved, search with a clear list, inspect before you sign, and close with people you trust. Take your time, ask questions, and keep your budget honest. The keys at the end of the journey are worth every careful step along the way.

Leave a Reply